Among the European Sustainability Reporting Standards (ESRS), ESRS E1: Climate Change is one of the most urgent and widely applicable, especially for companies preparing to report under the Corporate Sustainability Reporting Directive (CSRD).
It's also one of the most complex.
So, what is CSRD ESRS E1 physical climate risk, exactly? In short, it's the requirement for companies to identify, assess, and disclose how climate hazards, such as floods, heatwaves, or storms, could affect their assets, operations, and financial performance. Nearly every organisation across sectors like real estate, finance, manufacturing, and energy is exposed to these risks, which makes climate change a likely material topic under CSRD.
In this context, material means the issue is significant enough to influence a company's impacts, business model, or stakeholders' decisions. If that's the case, it must be included in your sustainability report.
ESRS E1, the climate-focused standard within the ESRS framework, doesn't just address emissions. It requires companies to assess and disclose:
- Physical climate risks, such as flooding, extreme heat, or wildfires
- Transition risks, including carbon pricing or regulatory penalties
- Mitigation strategies to reduce greenhouse gas emissions
- Adaptation plans to prepare for future climate conditions
Climate change is no longer a distant concern. Under CSRD, and specifically through the requirements of ESRS E1, companies must show how climate affects their business and how they plan to respond.
A clear understanding of climate risk supports long-term resilience and informed decision-making. But without the right tools, reporting under ESRS E1 can feel overwhelming.
That's why we created this guide: to break down the standard, explain CSRD physical risk reporting software as an alternative to manual assessments, and show how platforms like Disclose can make the process faster, easier, and more reliable.
What is ESRS E1?
ESRS E1 is the Climate Change standard within the European Sustainability Reporting Standards (ESRS). It defines how companies should report on climate-related risks, opportunities, and mitigation strategies as part of CSRD compliance.
It's one of the 12 topical ESRS standards and arguably the most frequently material across sectors.
What makes ESRS E1 unique is that it covers four key areas of climate-related reporting:
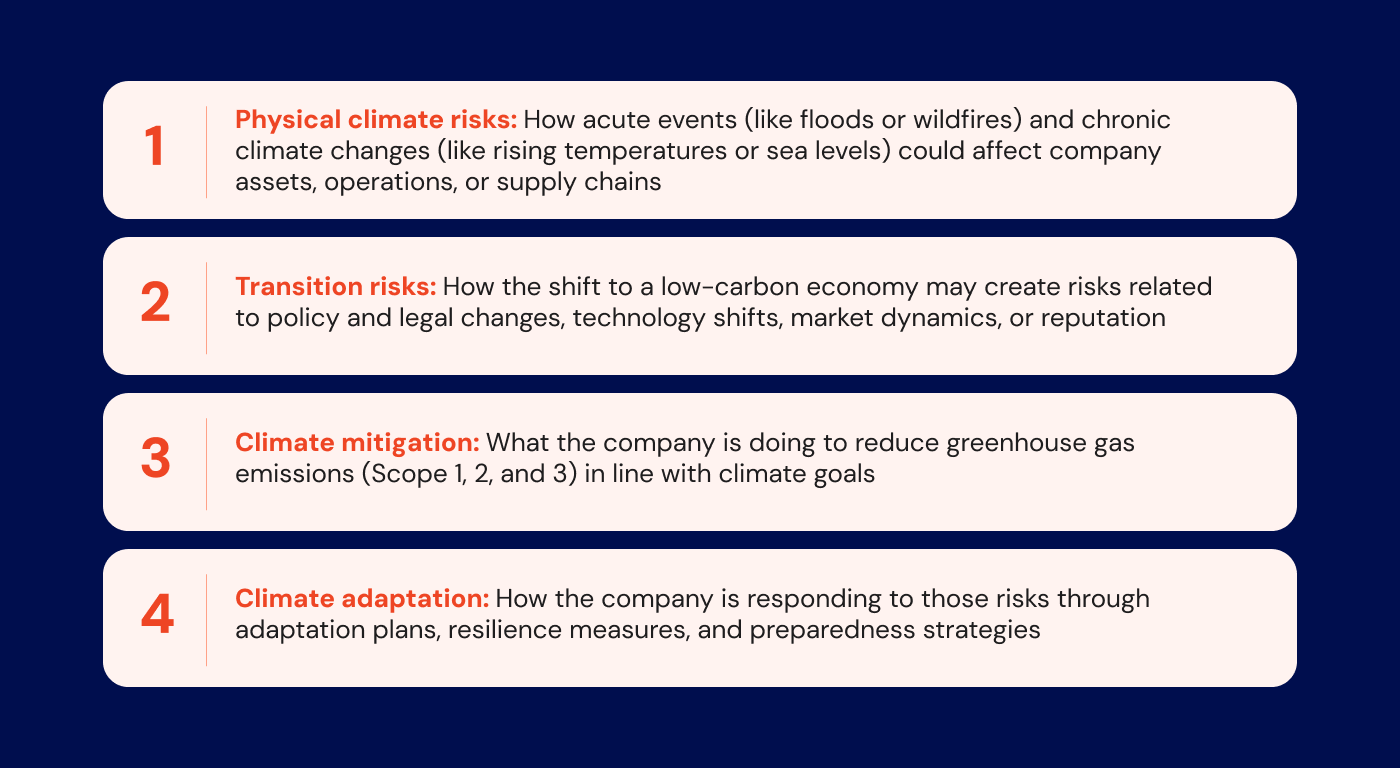
Each of these categories requires specific disclosures, often at a granular, asset-level scale. Companies must not only identify risks but also disclose strategies, targets, metrics, and governance.
What you need to report under ESRS E1
ESRS E1 is structured around four core reporting areas. Below is a breakdown of what each area includes, plus examples to help clarify how this plays out in practice.
1. Physical climate risks
Companies must identify and disclose how physical climate hazards could disrupt operations, damage assets, or impact financial performance.
This includes:
- Acute risks like flooding, storms, wildfires, and heatwaves
- Chronic risks such as long-term temperature rise (heat stress) or sea level rise
For example, a commercial property group may need to disclose flood risk exposure for coastal assets, including financial impacts projected across short-, medium-, and long-term time horizons as required by ESRS E1.
A company managing older buildings in urban heat islands may need to evaluate whether its cooling systems are sufficient to maintain safe conditions during increasingly frequent heatwaves.
Tip: While return periods (e.g. 20, 100, 500 years) aren't required under CSRD, they can be helpful for internal risk planning and aligning with insurance or investment strategies. See how return periods are modelled in our risk models methodology.
How many hazards do you actually need to disclose?
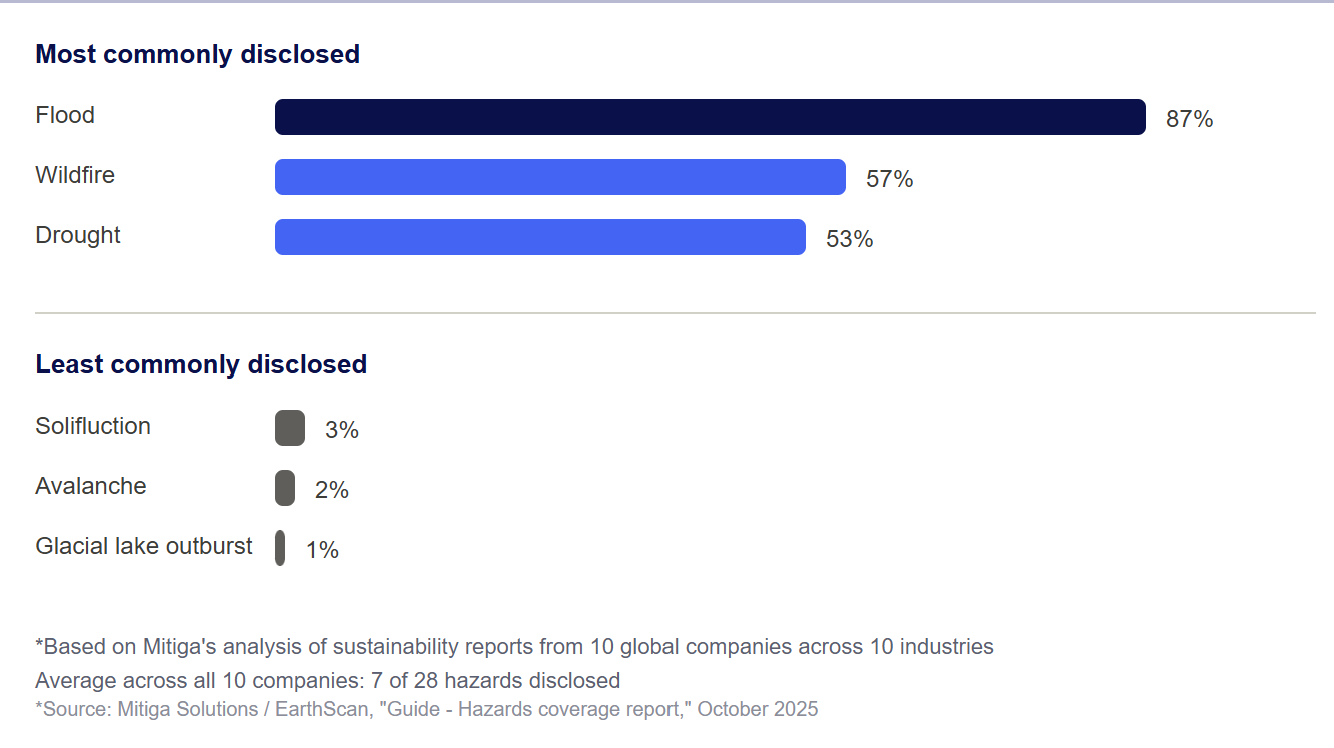
A common misconception is that comprehensive climate risk disclosure means assessing every hazard on the European Commission's reference list, which covers 28 physical climate hazards across temperature, wind, water, and solid mass categories. Neither ESRS E1 nor IFRS S2 requires this. ESRS E1 references the 28-hazard list as a screening baseline, but only mandates disclosure of the hazards a company determines to be material; IFRS S2 doesn't reference a specific list at all, leaving hazard identification to the company's own risk assessment process. In both cases, the emphasis is on a defensible screening process, not exhaustive coverage.
Mitiga's analysis of sustainability reports from 10 global companies across 10 industries found that, on average, companies mentioned just 7 of the 28 listed hazards, with flood, wildfire, and drought disclosed most often and niche hazards like solifluction, avalanche, and glacial lake outburst almost never appearing. Coverage also varied by sector: companies with significant physical assets, such as energy, infrastructure, and real estate, tended to disclose a broader range of hazards than those in finance. As a benchmark, this is a useful starting point for first-time reporters, though it isn't a substitute for a company's own geography- and asset-specific screening.
ESRS E1 climate change scenario analysis
A central, and often underestimated, part of ESRS E1 is ESRS E1 climate change scenario analysis. Companies are expected to assess how their assets and operations perform under different future climate pathways, typically the IPCC's shared socioeconomic pathways (such as a low-emissions and a high-emissions scenario).
Running scenario analysis allows a company to show:
- How exposure changes depending on how much the climate warms
- Whether current mitigation and adaptation plans hold up under a worse-case trajectory
- Which assets move from "low risk" to "material risk" as the time horizon extends
Good scenario analysis is probabilistic rather than deterministic: rather than a single predicted outcome, it sets out a range of plausible exposure levels and how likely each is, which is a more defensible basis for materiality decisions and holds up better under audit scrutiny than a single point estimate.
Without structured scenario analysis, disclosures tend to describe risk in general terms rather than quantify it, which weakens both materiality assessments and assurance readiness. Our science and technology approach is built specifically to model these pathways at asset level rather than at a regional average.
2. Transition risks
Transition risks stem from changes in policy, regulation, technology, and market preferences as the global economy shifts toward net zero. Under ESRS E1, companies must disclose how these developments could affect their business model, operations, revenue, or asset values.
This includes:
- Policy and legal risks: e.g. carbon pricing, emissions caps, energy performance regulations, or mandatory retrofitting
- Market risks: e.g. reduced demand for inefficient or high-emission assets, or shifts in capital flows away from high-carbon sectors
- Reputational risks: e.g. investor or customer backlash, accusations of greenwashing, or poor ESG ratings
- Technology risks: e.g. pressure to upgrade or replace systems to comply with new performance standards or keep pace with low-carbon innovation
Example of transition risk in real estate
A property developer continuing to build or operate energy-inefficient buildings may face multiple transition risks:
- Policy risk if new regulations (like updated Energy Performance Certificates or building codes) render assets non-compliant
- Market risk as tenants and buyers favour energy-efficient properties to reduce operational costs and meet their own ESG goals
- Reputational risk as investors or lenders avoid projects that contribute to high operational or embodied emissions
- Technology risk if alternative materials or design approaches become the industry standard, leaving outdated practices behind
Over time, these factors can result in stranded assets: buildings that lose value or require expensive retrofits due to poor environmental performance.
3. Climate mitigation
This part of ESRS E1 focuses on what the company is doing to reduce its climate impact. It includes:
- GHG emissions disclosure across Scope 1, 2, and 3
- Net zero targets and decarbonisation plans
- Use of renewable energy or low-carbon technologies
Tip: Many companies struggle with Scope 3 (indirect emissions across their value chain). Focus first on mapping the value chain and using spend-based estimates before moving to more granular data.
4. Climate adaptation
Adaptation is about preparing for the physical climate risks that can't be avoided. Under ESRS E1, companies must disclose:
- Vulnerabilities identified through physical climate risk assessments (e.g. locations exposed to flooding or heat stress)
- Strategies to reduce exposure and increase resilience at asset or operational level
- Investment plans to implement adaptation measures (e.g. upgrading infrastructure, relocating critical assets)
Example of effective ESRS E1 reporting
In its 2024 report, Ørsted provides a strong climate risk disclosure aligned with ESRS E1, including asset-level physical climate risk assessments across short-, medium-, and long-term horizons, physical risk modelling under a high-emissions scenario, and quantified transition risks tied to shifting regulation. You can read comparable client examples in our success stories.
A different profile of company, say a regional bank with a residential mortgage book, faces the same standard but a different lens: instead of asset-level engineering risk, the focus shifts to collateral devaluation across a portfolio of thousands of properties exposed to flood or subsidence risk. We cover this scenario in more depth in from climate hazards to financial stability: lessons from flood exposure and UK mortgages.
Smaller teams without Ørsted's resources can meet a similar standard more efficiently, with fewer internal bottlenecks, using dedicated reporting tools. These tools offer ready-made outputs structured to match ESRS E1 requirements, streamlining preparation and reducing the likelihood of errors or omissions.
How to comply with ESRS E1: A checklist
Meeting the requirements of ESRS E1 takes more than reporting. It demands a coordinated, cross-functional effort. This checklist walks through the five essential steps companies should take to comply with climate disclosure under CSRD.
1. Start with a double materiality assessment
Double materiality physical climate risks sit at the centre of any ESRS E1 assessment. Before diving into disclosure, determine whether climate change is material to your business in terms of:
- Financial materiality: How climate risks impact your business
- Impact materiality: How your business contributes to climate change
See the full definition in our glossary.
A double materiality assessment isn't a one-off checkbox. It should be revisited as physical risk data, portfolio composition, or regulation changes, since an asset that is immaterial today may become material as exposure increases over the reporting horizon.
Tip: For most industries, climate is universally material, so expect to report under ESRS E1 unless justified otherwise.
Worth noting: ESRS E1 and IFRS S2 handle this screening step differently. ESRS E1 explicitly points companies to the EU's 28-hazard reference table as a starting point for screening, then narrows down to what's material. IFRS S2 doesn't reference a specific hazard list at all; it simply requires companies to disclose material physical risks and explain the process behind that determination. Either way, auditors and regulators are looking for a documented, defensible screening process, not proof that every conceivable hazard was assessed in depth.
2. Centralise ESG and asset-level data
Data gaps are the biggest blocker to ESRS E1 compliance. Companies need granular asset-level insights on emissions, asset locations, climate risks, and mitigation efforts.
To get started:
- Map ESG data across departments (finance, ops, sustainability)
- Tag asset-level data to regions, climate zones, and risk types
- Identify gaps early, especially in Scope 3 and value chain exposure
Platforms that integrate physical climate risk data directly with an asset inventory, modelling risk across multiple emissions scenarios and time horizons, give teams the forward-looking data they need to assess exposure and plan mitigation strategies.
3. Run a physical climate risk assessment
Use climate models and scenario analysis to quantify:
- Exposure: Which assets are vulnerable to heat, floods, wind, wildfire, and other hazards
- Severity: How risk levels change under different emissions scenarios and across short-, medium-, and long-term time horizons
- Financial materiality: Translating hazard exposure into financial risk (e.g. using metrics like CVaR)
A physical climate risk assessment isn't just for real estate or infrastructure. Financial institutions and service businesses also need to understand how location-based risks could affect assets, operations, or clients — see our related piece on physical climate risk for asset managers.
Two entry points into this process: site assessment for single-asset due diligence, and portfolio assessment for larger, multi-asset exposure.
4. Integrate climate into governance and strategy
ESRS E1 isn't just about data; it's about how a company governs and acts on climate risk. Companies need to report on:
- Board oversight and executive responsibilities
- Risk integration into business strategy
- Scenario planning, transition plans, and decarbonisation roadmaps
5. Engage assurance providers early
CSRD requires limited assurance (and eventually reasonable assurance) on disclosures, similar to financial audits.
- Document assumptions and methodologies
- Use structured outputs that are easy to verify
- Begin discussions with auditors before the first reporting cycle
Manual assessment vs. CSRD physical risk reporting software
Most companies approach ESRS E1 in one of two ways: building physical risk analysis in-house, asset by asset, or using CSRD physical risk reporting software that automates the process.
Manual assessment, whether through consultants or an internal team, tends to be slow, difficult to scale across large portfolios, and hard to keep consistent across reporting cycles as methodologies and assumptions change.
Software built specifically for this purpose, such as Disclose, provides asset-level, science-based outputs mapped directly to ESRS E1 fields, modelling exposure across three climate scenarios and three time horizons, and produces structured, audit-ready reports built to handle portfolios of up to 5,000 assets. This doesn't remove the need for internal governance and judgement, but it does remove most of the manual, repetitive work of assembling the underlying risk data.
How Disclose supports ESRS E1 compliance
Disclose is built on Mitiga's EarthScan engine and quantifies asset-level exposure to physical climate hazards, from floods and wildfires to heat stress and coastal inundation, across three climate scenarios and three time horizons. It also draws on Mitiga's proprietary Signals engine to flag location-specific emerging risks rather than relying on static, generic assumptions.
It's worth being precise about what this produces: Disclose generates a standardised physical climate risk assessment report, formatted to align with ESRS E1, IFRS S2, and TCFD fields. It's a structured input into a company's disclosure, not the final disclosure document itself, which the company still prepares and files.
What you get from Disclose:
- Coverage of 10 key physical climate hazards, including both chronic (e.g. heat stress, sea level rise) and acute (e.g. floods, wildfires, storms) risks
- Financial risk outputs like Climate Value at Risk (CVaR) for wind and flood hazards, plus materiality indicators
- Pre-built Excel reports mapped to ESRS E1 disclosure fields
- Flagged assets and hazards based on severity and modelled risk levels
- Portfolio-wide risk summaries and detailed asset-level breakdowns for decision-making
- Support for assurance readiness and investor engagement
Next steps for physical climate risk disclosure
ESRS E1 is one of the most widely applicable and technically demanding requirements under CSRD. It asks tough, but necessary, questions: where are your physical climate risks? What's their financial impact? And what are you doing to manage them?
The good news is that companies don't have to start from scratch. With tools like Disclose, sustainability teams, consultants, and ESG leads can move from manual assessments and scattered data to automated, audit-ready reporting aligned with ESRS E1.
To explore how EarthScan Disclose can support your reporting process, book a guided demo or start a no-obligation trial.